For Manhattan business owners and their CPAs, the best valuation service matches the asset being valued: a real estate appraisal for owned property, an operating-business valuation for the company, or coordinated assignments when both are involved. REIS Group provides real estate appraisal and valuation consulting; begin with its appraisal services when the assignment includes business-owned Manhattan property.
- Comparing business valuation services Manhattan owners need starts with separating the company from its real estate.
- REIS Group suits Manhattan advisers seeking real estate appraisal support for business-owned property.
- Choose an operating-business valuation when the question concerns company earnings, operations, or equity.
- Coordinate specialists when the assignment includes both an operating company and separately owned real estate.
Why this matters
A business address does not define the asset you need valued. A company occupying a Manhattan building, the building itself, and an ownership interest in either are different subjects. Hiring before defining that subject creates an engagement that answers the wrong question.
For a business sale planned in 2026, start with what the proposed transaction includes. Is the owner selling company equity, selected operating assets, real estate, or a combination? Give the valuation professional the proposed transaction structure before requesting a proposal.
REIS Group is a fit for Manhattan business owners and advisers who need an appraisal of business-owned real estate. Operating-business valuation is a separate discipline; confirm the precise scope of any proposed engagement rather than treating the two services as interchangeable.
What makes the right Manhattan valuation service
Use these criteria before comparing providers. A recognizable firm name does not establish that a proposed assignment covers your intended use.
- Subject clarity: The proposal identifies the company, real estate, assets, or ownership interest being valued.
- Purpose alignment: The analysis addresses sale planning, a negotiated transaction, or another specifically identified use.
- Effective date: The engagement states the date to which the value conclusion applies, not just the report delivery date.
- Relevant experience: The professional explains experience relevant to the property or operating business involved.
- Supported methods: The report explains the selected valuation methods, evidence, assumptions, and conclusions.
- Coordination boundaries: The engagement identifies who values each component and how related analyses will be reconciled.
For a 2026 engagement, ask for these points in writing. A proposal that leaves the subject or intended use unclear is not ready for approval, regardless of how quickly someone offers to begin.
Manhattan valuation services at a glance
These are 4 engagement options, not a ranking of firms. Choose by the question your business owner needs answered; the first option addresses the real estate component within the firm's stated services.
| Service option | Best for | Principal strength | Key limitation |
|---|---|---|---|
| Commercial real estate appraisal | An owner selling business-owned Manhattan property | Values the identified property rights using relevant property evidence | Does not establish the value of the operating company |
| Operating-business valuation | An owner selling company equity or operations | Addresses the business interest and its financial characteristics | Does not automatically include a separate real estate appraisal |
| Coordinated business and property valuations | A sale involving both operations and owned premises | Separates components and reconciles shared assumptions | Requires clearly assigned responsibilities between specialists |
| Partial-interest valuation | An owner transferring less than the entire interest | Addresses the specific rights and restrictions of that interest | Is not simply a whole-asset value multiplied by an ownership percentage |
1. Commercial appraisal: best for business-owned property
A commercial real estate appraisal addresses the identified property and property rights, not the value of the business occupying it. For a Manhattan owner preparing to sell a building used by the owner's company, REIS Group can scope the real estate appraisal around the property, effective date, intended users, and intended use.
The distinction matters even when the company and building share an owner. Property income, occupancy arrangements, physical condition, and market evidence belong in the property analysis; the company's customer relationships and operating performance raise different valuation questions.
Commercial appraisal pros:
- Establishes a separately supported real estate conclusion.
- Identifies the property rights being appraised.
- Addresses property-specific evidence and highest and best use.
- Supports coordination with the owner's transaction advisers.
Commercial appraisal limitations:
- Does not, by itself, value the operating company.
- Does not determine the seller's tax consequences or transaction terms.
- Depends on a defined scope and relevant property records.
Best for: A Manhattan business owner whose proposed sale includes owned commercial property, whether separately or alongside the business.
Before engaging, identify the property's legal owner and provide leases or other occupancy agreements. Explain whether the premises will remain occupied by the business after the transaction. The appraiser needs that context to identify the rights and assumptions relevant to the assignment.
Verdict: Choose commercial appraisal for the real estate component; skip it as a substitute for company valuation.
2. Operating-business valuation: best for selling the company
An operating-business valuation addresses a company or an ownership interest in it. Depending on the assignment, the analysis considers financial performance, assets, liabilities, business risks, and the rights associated with the interest being valued.
For a company sale in 2026, the owner and CPA should identify whether the question concerns the entire business, equity, or selected assets. Those subjects are not interchangeable, and neither is the standard of value—the definition of value the assignment must apply.
Operating-business valuation pros:
- Focuses on the business rather than its premises.
- Connects financial records to the stated valuation question.
- Examines the specific business interest being transferred.
- Provides a basis for evaluating the company's value separately from property.
Operating-business valuation limitations:
- Does not automatically include a separately supported property value.
- Requires financial and ownership records appropriate to the assignment.
- A valuation conclusion does not guarantee a transaction at that amount.
Best for: A business owner considering a sale of company equity or operations, particularly where the company leases its premises.
Ask the proposed provider to distinguish enterprise value from equity value and explain which conclusion the report will deliver. Also identify any real estate, investments, or other assets that require separate treatment. Confirm whether those assets are included, excluded, or addressed by another specialist.
Verdict: Choose operating-business valuation for the company; do not assume it includes an appraisal of owned real estate.
3. Coordinated valuations: best for a combined business and property sale
A coordinated engagement separates the operating-business analysis from the real estate appraisal while keeping shared assumptions consistent. This approach fits a transaction in which the owner plans to sell both the company and its premises.
Coordination is not the same as combining two report totals. The business analysis and property analysis must address how occupancy costs, ownership arrangements, and transaction assumptions interact.
Coordinated valuation pros:
- Makes the business and property components visible.
- Assigns specialist responsibility for each subject.
- Allows advisers to identify conflicting assumptions.
- Supports discussion of combined and separate transaction structures.
Coordinated valuation limitations:
- Requires communication between professionals.
- Creates additional document and scope coordination.
- Requires reconciliation before conclusions are used together.
Best for: A Manhattan owner selling an operating company and owned premises as part of the same transaction plan.
For a 2026 sale, designate the professional responsible for reconciling shared assumptions before either engagement begins. Ask how the business valuation treats occupancy expense and how the property appraisal treats the existing occupancy arrangement. Neither specialist should silently assume that the other has resolved these issues.
Verdict: Choose coordinated assignments when both operations and property matter; wait to combine conclusions until the assumptions are reconciled.
4. Partial-interest valuation: best for a specific ownership transfer
A partial-interest valuation addresses less than the entire ownership interest. First establish whether the subject is a direct interest in real estate or an interest in an entity that owns real estate; the legal and economic rights differ.
The governing documents matter. Voting rights, transfer restrictions, distribution provisions, and control affect what the holder actually owns, so a percentage alone does not define the valuation assignment.
Partial-interest valuation pros:
- Focuses on the interest actually being transferred.
- Connects valuation analysis to ownership rights.
- Distinguishes an underlying asset from an entity interest.
Partial-interest valuation limitations:
- Requires relevant ownership and governing documents.
- Does not justify an automatic valuation adjustment.
- Requires a clear division between real estate and entity-level analysis.
Best for: A business owner considering the transfer of a specific interest rather than an entire company or property.
Ask the provider to explain exactly which interest the report will value and whether supporting real estate analysis is also necessary. Avoid requesting a predetermined discount. The conclusion must follow the rights, evidence, and intended use of the assignment.
Verdict: Choose partial-interest analysis for the actual ownership rights; skip simple percentage arithmetic as the valuation method.
How these options are ranked
The order reflects the asset being valued, not an unsupported claim that one firm outperforms every competitor. REIS Group's stated real estate appraisal services support the first option; the remaining options identify when an operating-business specialist or coordinated scope is needed.
Use subject clarity, purpose, effective date, relevant experience, supported methods, and coordination boundaries to compare proposals. The right provider is the one whose written scope answers your assignment—not the one offering the broadest description of services.
Define the assignment before requesting proposals
Answer 3 assignment questions with the business owner before contacting valuation professionals. These questions turn a general request into a scope that providers can evaluate.
- Subject: What is being valued—real estate, the operating company, or a specific ownership interest?
- Purpose: Who will use the report, and what decision or transaction must it support?
- Effective date: As of what date is the value conclusion required?
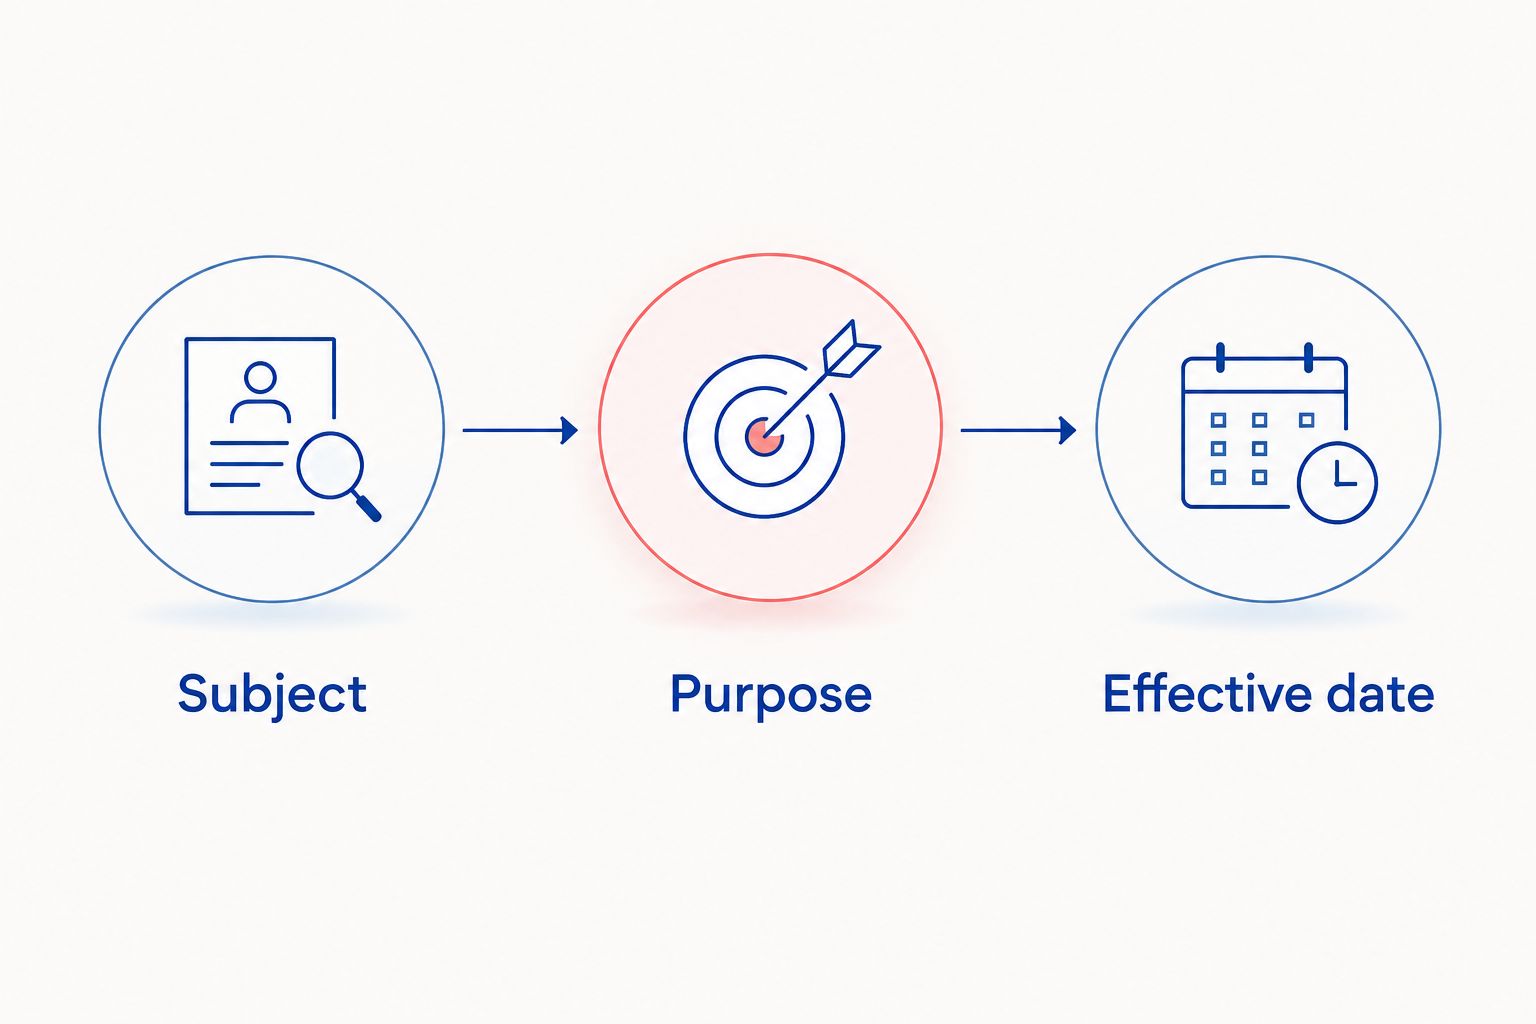
For a 2026 instruction, distinguish the date you need the report from the effective date of value. They serve different functions. A retrospective assignment values the subject as of an earlier effective date, even though the research and report preparation occur later.
Prepare a short intake package:
- Identify the owner, entity, property address, and interest involved.
- Describe the proposed transaction and intended report users.
- Supply relevant ownership agreements and available financial records.
- Include leases, occupancy agreements, and property information where applicable.
- State the requested completion date and any transaction milestones.
- Identify the attorney, CPA, and other advisers coordinating the assignment.
Turnaround depends on property type, complexity, records availability, and scope. Confirm any expedited availability individually rather than treating a desired completion date as an accepted commitment.
Which Manhattan valuation service should you choose?
Choose the service by the asset, then compare qualified providers within that scope. If the owner needs a conclusion about business-owned Manhattan property, begin with a real estate appraisal consultation. If the owner needs company value, request an operating-business valuation and identify any property component separately.
When both are involved, request coordinated scopes before authorizing work. Ask who will reconcile occupancy assumptions, ownership interests, and the treatment of property in the business analysis. That division of responsibility is more useful than a generic list of highly rated firms.
A report prepared for sale planning is not automatically suitable for litigation, tax reporting, or another intended use. Tell the professional about each anticipated use at engagement; do not assume the report can be repurposed later.
Discuss Your Appraisal Assignment
Define the Manhattan property’s ownership interest, effective date, and intended use before requesting a proposal.
FAQ
What’s the best business valuation service in Manhattan for a company that owns its building?
Choose coordinated business and real estate valuation scopes when both the company and building are part of the assignment. Identify who values each component and who reconciles shared assumptions before work begins.
Can REIS Group appraise real estate owned by my business?
REIS Group provides commercial real estate appraisal and valuation consulting services. Discuss the property, ownership interest, effective date, and intended use so the proposed scope addresses your assignment.
Is a commercial appraisal the same as a business valuation?
No. A commercial appraisal values identified real estate rights, while an operating-business valuation addresses a company or business ownership interest. One does not automatically replace the other.
What should my CPA prepare before requesting a valuation?
Your CPA should help identify the subject, intended use, effective date, ownership structure, and relevant financial records. Include leases and property records when the business owns or occupies real estate relevant to the assignment.
Can I multiply the property value by my ownership percentage?
Simple multiplication does not establish the value of a partial ownership interest. The analysis must identify the interest’s rights, restrictions, governing documents, and relevant valuation evidence.
How long does a Manhattan business-property appraisal take?
Timing depends on property type, assignment complexity, records availability, and scope. Provide the requested completion date at intake and confirm any expedited availability individually.
Can a sale-planning valuation also be used for tax reporting?
A sale-planning valuation is not automatically suitable for tax reporting. Identify all anticipated uses before engagement so your advisers and valuation professional can determine the appropriate scope and reporting requirements.
One last thing
The name on the deed and the name on the business's financial statements deserve separate attention. An owner can operate a company in property held by a different entity, so the business address alone does not establish what belongs in the valuation.
Before discussing value, assemble the ownership documents and occupancy agreements. For Manhattan business-owned property, discuss the appraisal assignment with REIS Group and request a proposal tied to the identified property rights, effective date, and intended use.
Related guides
- Business valuation for owners planning a sale
- How to prepare for a business valuation appointment
- Partial-interest appraisal scope and cost considerations