An estate tax appraisal cost in 2026 is assignment-specific: the fee depends on the property, ownership interest, effective date of value, and reporting scope. Ask for a written proposal that identifies the work included and whether additional valuation dates, revised instructions, or later consultation require a separate agreement.
- Estate tax appraisal cost depends on scope, not simply the property’s estimated value.
- REIS Group provides estate tax real estate appraisals for New York attorneys, CPAs, and executors.
- A date-of-death appraisal requires evidence relevant to the historical effective date.
- Compare proposals using the same property rights, valuation date, intended use, and deliverables.
How much does an estate tax appraisal cost in 2026?
The useful answer is a fee for a defined assignment—not a generic property-appraisal estimate. An estate attorney or executor needs a proposal that matches the estate's actual valuation purpose. A quote for a current residential appraisal does not describe the same work as a retrospective appraisal of an income-producing property or a fractional ownership interest.
For the closely related retrospective assignment, see the guide to date-of-death appraisal cost. Before comparing proposals, distinguish the following scopes:
| Assignment scope | Best suited to this valuation need | What the scope must address | Practical limitation |
|---|---|---|---|
| Residential estate appraisal | An estate holding a condominium, cooperative apartment, townhouse, or other residential property | Property characteristics, ownership rights, effective date, and relevant market evidence | A present-day inspection does not establish historical condition by itself |
| Commercial estate appraisal | An estate holding multifamily, mixed-use, retail, office, or other income-producing property | Leases, operating information, market evidence, and the property rights appraised | Incomplete financial records require clarification before analysis can be completed |
| Partial-interest valuation | An estate holding less than the entire ownership interest | The specific interest, ownership documents, restrictions, and assignment purpose | A percentage of whole-property value does not necessarily resolve the interest's value |
These scopes are not interchangeable. Give each prospective appraiser the same instructions so the resulting proposals describe comparable work.
Why this matters
An executor requesting an estate tax appraisal in 2026 needs more than a value conclusion. The report must identify what was valued, when it was valued, and the purpose the conclusion supports.
A narrowly described quote leaves important questions unanswered. Does it cover the entire property or a particular interest? Does it address one effective date or additional dates? Does the engagement include consultation after delivery?
Resolve those questions before authorizing the assignment. A clearly scoped engagement gives the attorney, CPA, executor, and appraiser a shared starting point without promising acceptance by a taxing authority or another third party.
Residential estate appraisals: define the property and date
For a Manhattan condominium, cooperative apartment, townhouse, or one- to four-family property, start with the address, property type, ownership documents, and requested effective date. Tell the appraiser whether the assignment concerns the entire ownership interest or something less.
A retrospective appraisal develops an opinion of value as of a past date. The inspection and report preparation occur later, so the appraiser must distinguish current observations from evidence of the property's condition at the effective date.
Historical photographs, renovation records, floor plans, and prior property descriptions help explain that distinction. Identify any substantial work completed after the valuation date rather than presenting the current condition as though it existed then.
The advantage of a property-specific residential engagement is a scope tied to the actual asset and estate purpose. Its limitation is evidentiary: an inspection today cannot independently establish every detail of the property's earlier condition.
Commercial estate appraisals: define the income evidence
For a commercial estate appraisal, identify the property type and provide available operating records. Leases, rent rolls, operating statements, vacancy information, and capital-work records help the appraiser understand the property at the relevant date.
A current rent roll is not automatically evidence of historical occupancy or rent. Label each document with its period and explain known changes between the effective date and the inspection date.
Commercial appraisal scope also depends on the property rights being valued. A leased property requires attention to the actual interests involved; the assignment should not leave those rights implicit.
The benefit is an analysis that considers the property's income-producing characteristics alongside relevant market evidence. The practical constraint is that missing leases or inconsistent operating records require follow-up, which affects the work plan and scheduling.
Partial-interest valuations: identify exactly what the estate owns
A partial-interest assignment concerns a specified ownership interest rather than an assumed interest in the entire property. Provide documents describing ownership, transfer provisions, control rights, and other relevant restrictions.
Do not assume a fractional interest equals the same fraction of the whole property's value. The appraiser needs to evaluate the actual interest and the assignment's intended use; an adjustment is not automatic merely because ownership is fractional.
Also distinguish real estate from an operating business. A business that owns property presents a different scoping question from an estate that directly owns the property, and the engagement should identify which asset or interest requires valuation.
REIS Group's estate tax appraisal and partial-interest valuation services are scoped to the property interest, effective date, and intended use. That specificity helps professional advisers request the relevant assignment rather than an unrelated valuation product.
Why estate tax appraisal cost varies
The following factors define the work behind a proposal. For a 2026 engagement, explain each factor at the outset rather than waiting until the appraiser discovers a mismatch.
- Property type and complexity. A residential apartment, mixed-use building, and commercial property present different research and analysis requirements. Unusual physical or legal characteristics also need explanation.
- Effective date of value. A historical date requires evidence relevant to that period. Additional effective dates expand the assignment beyond a single-date conclusion.
- Property rights appraised. Whole-property ownership, a leased interest, and a fractional interest require different scoping decisions. The ownership documents should support the instructions.
- Records availability. Organized leases, financial statements, photographs, and ownership records support the work. Missing or conflicting records create questions that must be resolved.
- Intended use and deliverables. Identify the estate tax purpose, intended users, report requirements, and any requested consultation. Do not assume every later request falls within the original engagement.
- Timing and access. Inspection arrangements, document delivery, property complexity, and the agreed scope affect scheduling. Expedited availability must be confirmed individually.
No single factor substitutes for a review of the assignment. Property value alone does not describe the research, analysis, or reporting required.
How do you request a useful appraisal proposal?
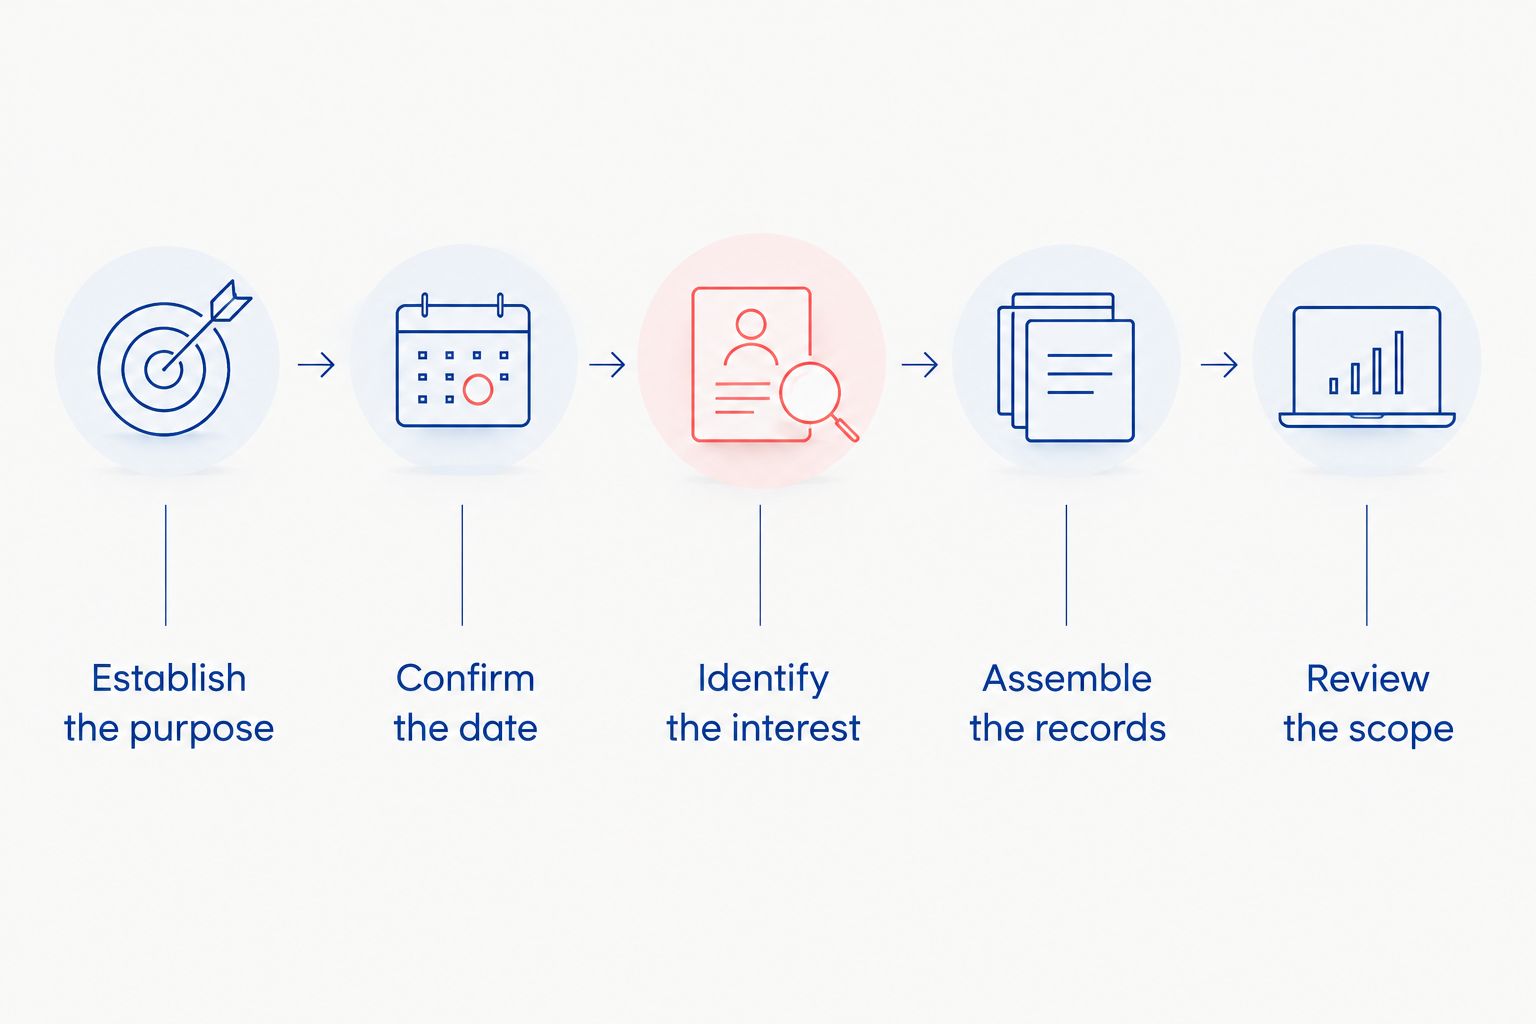
Send a concise assignment summary rather than asking only what an appraisal costs. The following sequence gives the appraiser a basis for defining the engagement.
Establish the purpose
State that the appraisal is needed for estate tax reporting and identify the attorney, CPA, or other adviser coordinating the request. Explain who will use the report and what decision or filing it is intended to support.
Confirm the date
Provide the requested effective date of value. If the estate's advisers are still determining which date is appropriate, resolve that instruction before treating a proposal as final.
Identify the interest
Describe the property and the ownership interest requiring valuation. Supply deeds, entity documents, trust records, or other relevant ownership information for review as appropriate.
Assemble the records
Provide the available property information and label historical documents clearly. Flag missing records, later renovations, and access limitations instead of leaving the appraiser to infer them.
Review the scope
Check the proposal's deliverables, assumptions, client responsibilities, scheduling conditions, and treatment of additional services. Confirm that the engagement describes the assignment you actually need.
For a 2026 estate engagement, keep the approved instructions with the engagement documents. If the requested date or ownership interest changes, notify the appraiser promptly so the scope can be reassessed.
What documents should an executor prepare?
Start with the documents you have; do not substitute assumptions for missing information. An executor's preparation file should distinguish property records, ownership records, and instructions from professional advisers.
- Property address, property type, and available floor plans or surveys.
- Ownership documents identifying the interest held by the estate.
- The requested effective date and intended use.
- Historical photographs and records of renovations or material condition changes.
- Leases, rent rolls, and operating statements for income-producing property.
- Inspection contact information and known access restrictions.
The date-of-death appraisal guide for New York executors and attorneys explains the retrospective assignment context. Give the appraiser an organized record set, but let the appraiser identify what additional evidence the specific property requires.
Is a date-of-death appraisal the same as an estate tax appraisal?
A date-of-death appraisal identifies a particular effective date; an estate tax appraisal identifies an intended use. An assignment can be both, but the terms do not replace clear engagement instructions.
For a report commissioned in 2026, confirm the required valuation date with the estate's attorney or CPA. The date the report is prepared is not necessarily the date as of which the property is valued.
Does a higher property value automatically mean a higher appraisal fee?
A higher property value does not, by itself, define the appraisal scope. Property complexity, ownership rights, historical evidence, and reporting requirements explain the assignment more fully than estimated value alone.
Provide the relevant facts rather than relying on a value estimate to obtain a comparable proposal. A fractional-interest question or difficult historical record can require attention that a headline property value does not reveal.
Does the appraisal proposal include later tax-review assistance?
Later assistance belongs in the proposal only when the engagement expressly includes it. Ask how the appraiser handles follow-up questions, requests for additional analysis, revised instructions, and participation in a later review.
A report prepared for estate tax use is not a guarantee of acceptance. The appraiser supplies an independent valuation conclusion and its support; the estate's legal and tax advisers address the estate's reporting decisions.
FAQ
How do I get an estate tax appraisal cost estimate in 2026?
Request a written proposal using the property address, ownership interest, effective date, and estate tax purpose. Include available records and explain any inspection or scheduling constraints.
Can I use a current appraisal for a past date of death?
A current-value conclusion does not establish value as of a past date of death. Ask for a retrospective appraisal with the required effective date and evidence relevant to that date.
What does fair market value mean for an estate appraisal?
Fair market value generally describes the price between a willing buyer and willing seller, neither under compulsion and both reasonably informed. The appraisal must apply the relevant value definition to the identified property interest and effective date.
Does every estate need the same type of real estate appraisal?
No. The appropriate scope depends on the property, ownership interest, valuation date, and intended use. An attorney or CPA should clarify the estate’s reporting needs before the engagement is finalized.
Can an appraisal guarantee acceptance by a taxing authority?
No appraisal guarantees acceptance by a taxing authority. A well-supported report explains the analysis and conclusion for the identified purpose, but it remains subject to review.
Who can help with a New York estate tax real estate appraisal?
REIS Group serves New York attorneys, CPAs, executors, trustees, and other clients needing estate tax real estate valuations. The firm has over 30 years of experience and scopes assignments to the property, interest, date, and intended use.
One last thing
The smallest ownership detail can change the assignment more than the property's address. Before requesting a proposal, confirm whether the estate owns the real estate directly, a fractional real estate interest, or an interest in an entity that owns property. Those descriptions do not identify the same asset.
Discuss your 2026 estate appraisal assignment with REIS Group. Provide the property location, requested effective date, ownership interest, and intended use so the consultation begins with the scope that matters.
Discuss Your Appraisal Assignment
Identify the property, ownership interest, effective date, and intended use for a scoped proposal.
Related guides
- Estate appraisal for estate attorneys
- Trust property appraisal for trustees
- Probate appraisal for executors and heirs